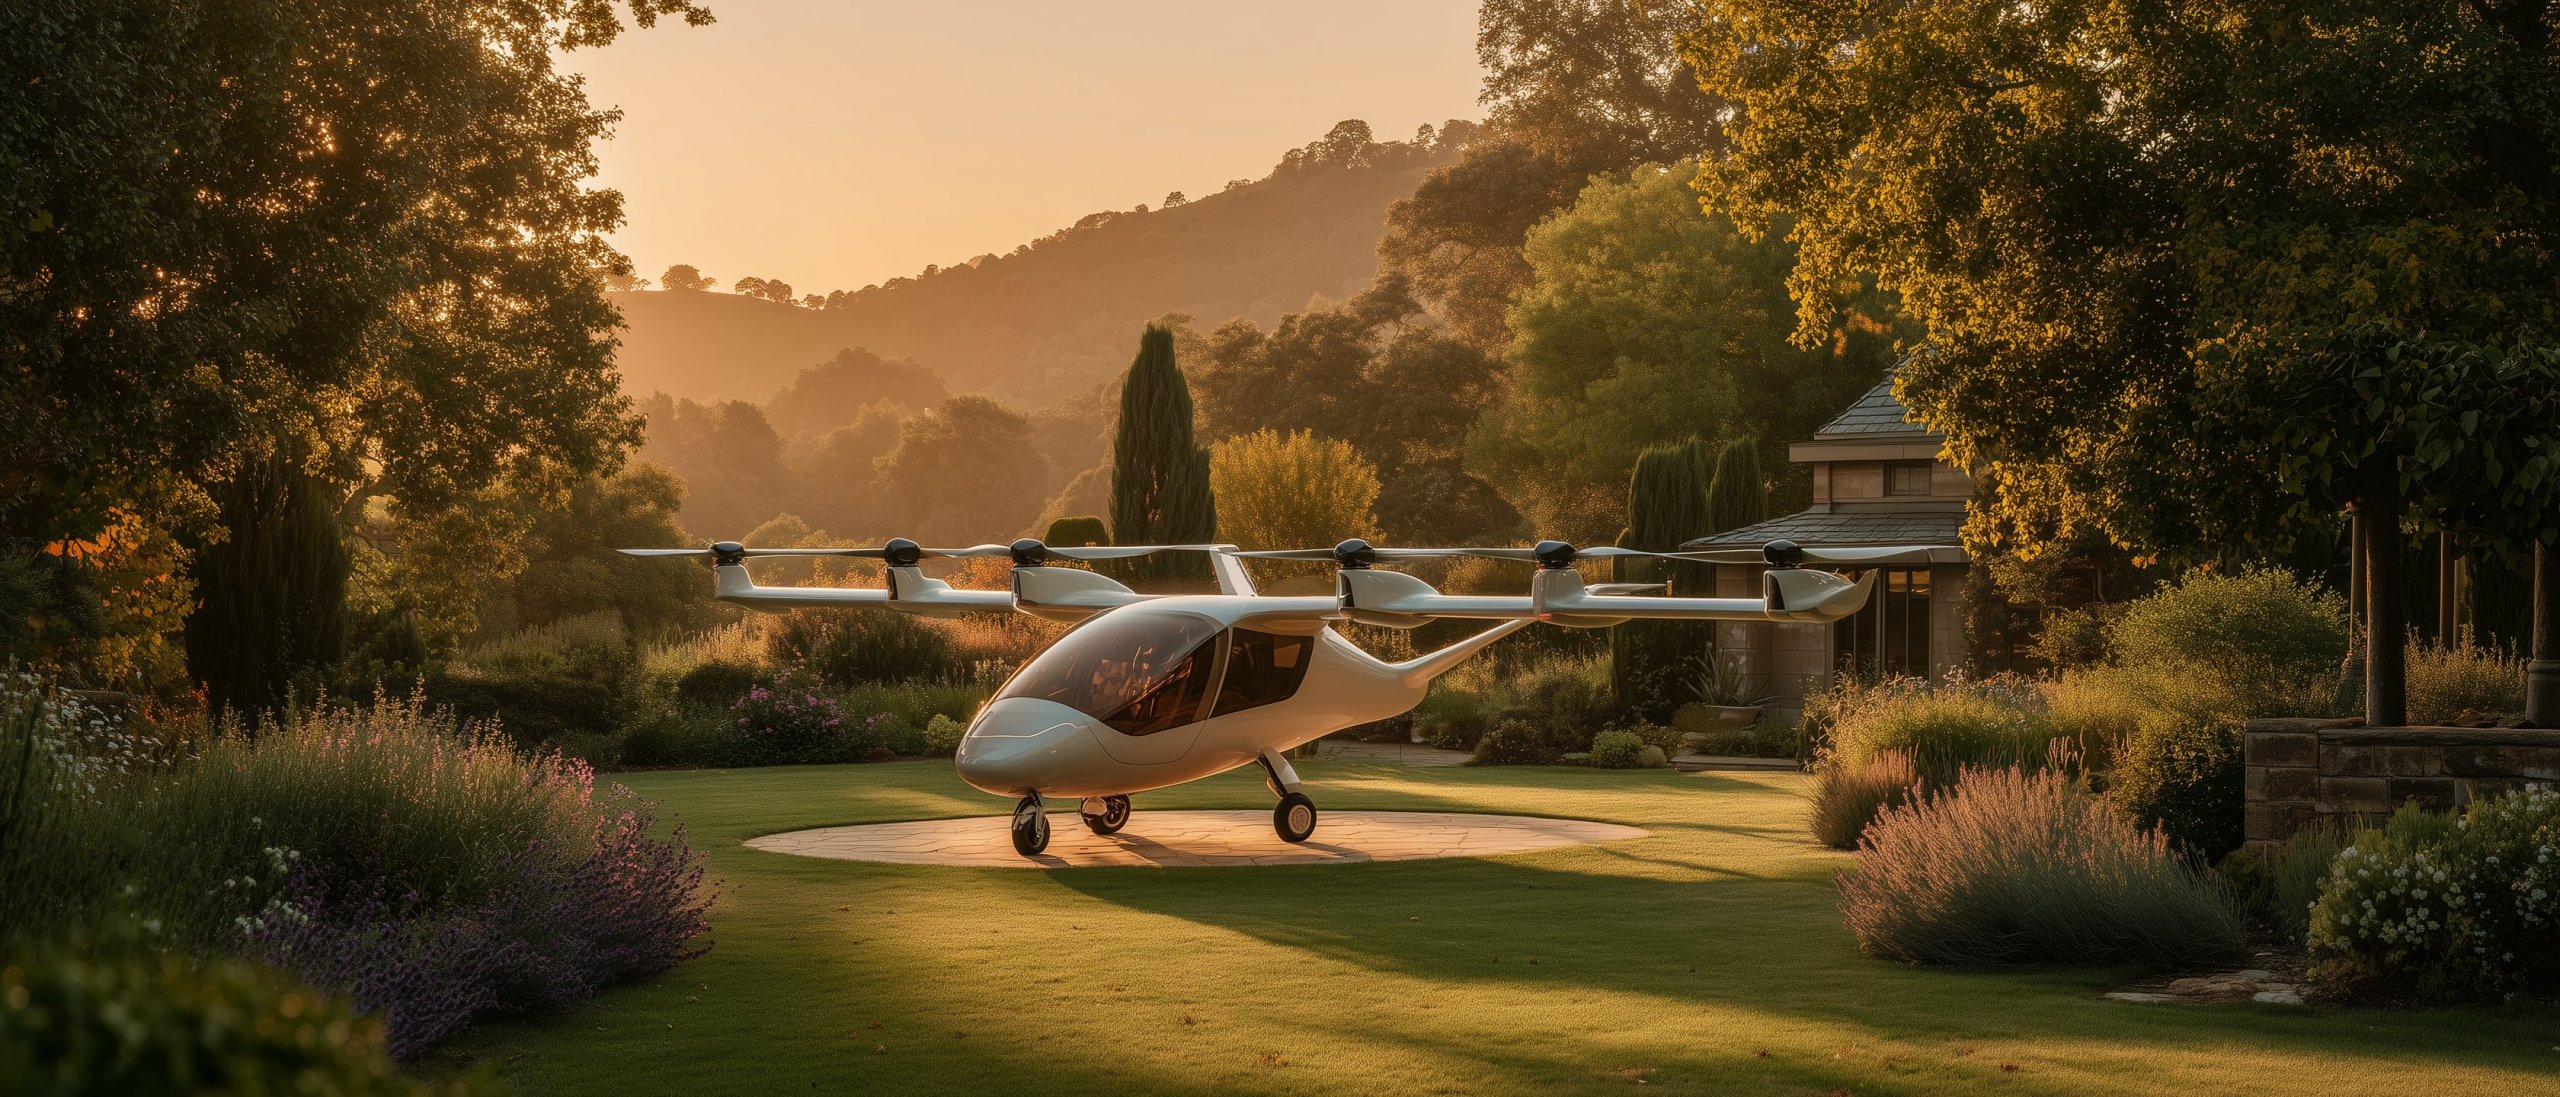
The architectural difference between an eVTOL and a helicopter is propulsion. The helicopter generates lift and thrust through a single large rotor driven by a turbine engine, with a tail rotor counteracting the main rotor’s torque. The eVTOL distributes lift and thrust across multiple smaller rotors or tilting propellers driven by electric motors, drawing power from substantial battery packs. The distributed-propulsion architecture produces a different aircraft: quieter at the same lift, more redundant against single-point failures, lower operating cost per flight hour, and dependent on charging rather than fueling for operational turnaround.
What this architecture buys is meaningful at the short-haul scale eVTOL is designed for. The noise floor is dramatically lower than the helicopter equivalent — Joby Aviation’s target is around forty-five decibels at one thousand feet during hover, where conventional helicopters operate in the seventy- to eighty-decibel range. The operating cost per flight hour is a fraction of helicopter operating cost because there is no turbine, no complex transmission, and far fewer moving parts. The maintenance burden drops correspondingly. What this architecture costs is range. The current generation of eVTOL platforms operates with ranges of one hundred to one hundred fifty nautical miles, against several hundred for the conventional helicopter — a hard limit set by current battery energy density that improves only as the underlying battery technology matures.
For an estate making aviation infrastructure decisions now, the eVTOL question is not whether the category will arrive — the platforms are arriving — but whether the property’s pad and electrical infrastructure can accommodate it when the family decides to operate one. The answer turns on a single architectural decision made at master planning: whether the helipad is provisioned for megawatt-class charging and the ground-support equipment eVTOL requires, or built as a pure rotary pad that would need substantial retrofit to support eVTOL later. The infrastructure decision is treated under Aviation; this page treats the platforms themselves.
The platforms
Several platforms are at or near commercial type certification, with the field having narrowed substantially over the last two years as the early-cycle competitors who could not solve the engineering and economic problems exited the category.
Joby Aviation S4. The four-passenger-plus-pilot platform leading the certification race. Joby reached Stage 4 of the FAA’s five-stage type certification process in November 2025 — the first eVTOL to do so — and began power-on testing of the first FAA-conforming aircraft the same month. Initial commercial operations were targeted to begin in Dubai, with subsequent rollout in New York and Los Angeles markets through a Delta Air Lines partnership. The S4 has a range of approximately one hundred fifty nautical miles and a cruise speed near two hundred miles per hour. Joby accumulated more than nine thousand miles of test flight in 2025 alone.
Archer Aviation Midnight. The four-passenger platform from the second of the two American front-runners. Archer remains in Stage 3 of FAA type certification with a substantial flight-test program underway: fifty-five-mile flights, speeds above one hundred fifty miles per hour at ten thousand feet, the expanded flight envelope that supports the certification campaign. The company has a manufacturing partnership with Stellantis and a launch agreement with United Airlines, with plans for air taxi networks in Miami and other major metros.
Beta Technologies ALIA. The Vermont-based developer with two variants: ALIA-250 in conventional-takeoff configuration and ALIA-A as the full eVTOL. Beta operates with a less public posture than Joby or Archer but has substantial flight-test progress, a working charging-infrastructure deployment, and an established defense-and-cargo customer pipeline that gives the program revenue trajectory independent of passenger eVTOL certification.
Vertical Aerospace VX4. The four-passenger UK-developed platform targeting EASA and FAA certification with a production prototype in flight testing. Vertical has commercial pre-orders from American Airlines, Virgin Atlantic, Japan Airlines, and Avolon, representing one of the larger order books in the category by stated value.
Wisk Aero. The Boeing-backed program pursuing fully autonomous eVTOL certification under a separate regulatory pathway from the piloted platforms. Wisk’s certification timeline is less public than its piloted-eVTOL peers, but the architectural commitment to no-pilot operation is structurally different from the rest of the category and worth watching as a long-term competitor.
Volocopter and Eve Air Mobility. Regional players outside the US-centric Joby/Archer/Beta race. Volocopter received limited EASA certification for the VoloCity in 2025, the first commercial eVTOL approval in any major jurisdiction, though scoped narrowly. Eve, the Embraer-backed program, has provisional operating approvals in São Paulo and pursues the Latin American market initially.
Lilium (cautionary). The German seven-seat jet-style eVTOL program declared insolvency in November 2024 after failing to secure timely EASA certification and adequate funding. Lilium’s exit is the category’s clearest signal that the engineering and economic difficulty is genuine — the eVTOL category will produce significant casualties before it stabilizes, and identifying the platforms that survive matters more than identifying the platforms that fly first.
The architectural difference between an eVTOL and a helicopter is propulsion. Everything else — the noise floor, the operating cost, the range limit, the certification path — follows from that.
The certification state
The FAA type certification process for eVTOL operates in five stages, with each stage requiring increasingly detailed compliance demonstration. Stage 3 is the active flight-test campaign that demonstrates the aircraft meets the airworthiness standards. Stage 4 is the Type Inspection Authorization phase that confirms the production aircraft conforms to the certified design. Stage 5 is final type certification authorizing commercial operation.
Joby’s Stage 4 milestone in November 2025 — the first achieved in the category — marks the point at which the FAA is sufficiently confident in the aircraft’s design to allow conformity testing of production-representative aircraft. Final type certification follows, with commercial operations enabled once supplemental operational and pilot training certifications are complete. The category is no longer years away from passenger service; it is approaching it on a quarterly horizon for the platforms that have cleared the late-stage gates.
EASA operates a parallel certification process for European platforms with comparable rigor. Volocopter’s limited EASA certification was the first commercial eVTOL approval in any major jurisdiction, though scoped narrowly. The convergence of FAA and EASA standards is partial: some platforms certify under both, others target one jurisdiction first.
Operational characteristics
Several characteristics distinguish how eVTOL operates from how the helicopter operates, with substantial implications for the family that adopts one.
Noise. The dominant marketing argument for eVTOL is acoustic. The current generation targets noise levels in the forty-five-decibel range at one thousand feet during hover, against seventy to eighty for conventional helicopters. The architectural reason is distributed propulsion: multiple smaller rotors at higher RPM produce different noise signatures than a single large rotor, with the noise concentrated at frequencies easier to attenuate. Whether this translates to genuinely unobjectionable operation in residential settings remains a question the operational reality will answer.
Operating cost. The electric powertrain produces dramatically lower direct operating cost per flight hour than the turbine helicopter. No fuel burn at the cost of hydrocarbon aviation fuel. Substantially reduced maintenance burden because there is no turbine, no complex gearbox, no thousand-hour overhauls of mechanical systems with limited service life. The operating-cost differential is one of the architectural advantages the category is engineered around.
Range. The current generation operates with one hundred to one hundred fifty nautical miles of range, against several hundred for conventional helicopters. The range is a hard constraint set by current battery energy density. The range improves as batteries improve; the trajectory is real but slow.
Charging versus fueling. Operational turnaround is a different rhythm. The helicopter is refueled in minutes from a fuel truck or fixed storage. The eVTOL is charged in tens of minutes from megawatt-class electrical infrastructure. The operational pattern shifts toward longer ground times between flights, partially offset by the substantially shorter pre-flight and post-flight maintenance cycles.
Weather and conditions. The current eVTOL generation operates within narrower envelope limits than the conventional helicopter — limits on wind, on visibility, on icing conditions, on operating altitude. The platforms are certifying initially for visual-flight-rules operation in benign conditions, with all-weather and instrument-flight-rules capability arriving incrementally. For estates where weather is routinely challenging, the helicopter retains operational advantages eVTOL will not match for some time.
How eVTOL fits within Aviation
eVTOL sits alongside Helicopters and Seaplanes as the three sub-categories of aircraft that operate from the sovereign estate. Across the three, eVTOL is the newest and the least mature, with the most uncertainty about platform survival and the clearest trajectory toward becoming the dominant short-haul executive aircraft over the next decade.
What this means for the family planning estate aviation now is the hybrid-pad commitment treated under Aviation. The helicopter remains the right operational answer today; eVTOL is the platform the infrastructure should be ready to accept when the family chooses to operate one. The eVTOL platform itself will be selected from the field of survivors over the next few years, not committed to specifically at the master-planning stage. The infrastructure commitment — the megawatt-class electrical service, the pad provisioning, the ground-support architecture — is the commitment made now.
eVTOL is the category arriving at the boundary between aspirational and operational. The platforms have crossed from prototype to type certification. The commercial operations are beginning. The infrastructure decisions estates make today determine whether the family can adopt the platforms as they enter service or has to retrofit substantially when the time comes. The category will not arrive uniformly; some platforms will succeed, others will fail, the field will shift over the rest of the decade. What is no longer in question is that eVTOL is part of estate aviation’s near future. The discipline is to build for it now.